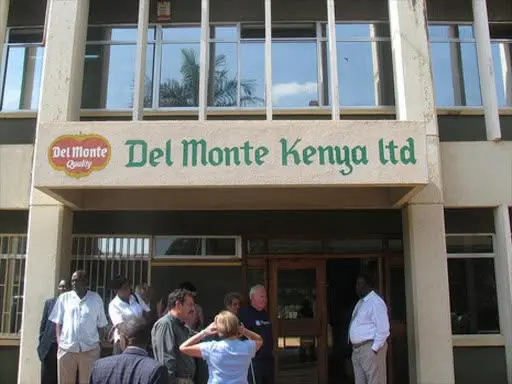
(NAIROBI, KENYA) – Kenya’s tax appeals tribunal has upheld a KES 1.7 billion ($13,076) withholding tax demand on fruit processor Del Monte Kenya over profits from transactions with foreign related companies.
The ruling confirms that the Kenya Revenue Authority can treat extra profits from deals between related companies as deemed dividends and tax them, even when no actual dividends have been paid to shareholders.
Del Monte had challenged the assessment. It argued that the tax authority could not treat the disputed profits as dividends before the main transfer pricing dispute was resolved.
The dispute arose from Del Monte Kenya’s sales of fresh and processed pineapples to its Swiss affiliate, Del Monte International GmbH. It also involved payments to related companies for agricultural inputs, production materials, spare parts, software and administration services. The tax authority also questioned interest expenses on an intercompany loan from Del Monte Fund BV.
Following an audit of the company’s transfer pricing arrangements for 2019 to 2021, the tax authority adjusted its taxable income. It treated KES 10.6 billion ($81.5 million) as dividends deemed distributed to foreign shareholders. It then imposed KES 1.7 billion ($13,076) in withholding tax, including penalties and interest.
The tribunal, chaired by Mutiso Makau, dismissed Del Monte’s appeal and upheld the assessment.
Transfer pricing refers to the prices companies within the same group charge one another. Tax authorities examine these transactions to ensure profits are properly reported and taxed in the countries where they arise.
The tax authority made its main transfer pricing adjustment on 20th December 2024, increasing the income it considered taxable in Kenya. Since dividends paid to non-residents attract 15% withholding tax, the authority applied the rate to the deemed distribution.
It issued the withholding tax assessment on 30th July 2025. Del Monte objected, but the tax authority confirmed the demand on 30th October 2025, prompting the company to appeal.
Del Monte argued that the withholding tax demand depended on the validity of the main transfer pricing adjustment, which it had challenged separately. It said the second assessment was premature because the underlying appeal was still pending when the tax authority raised the demand.
The company also accused the tax authority of ignoring the functions performed, assets used and risks assumed by the Kenyan entity and its related parties. It said its pricing method better reflected the transactions. It also challenged the disallowance of related party expenses and interest on the intercompany loan.
It further argued that the secondary adjustment required independent justification and that the tax authority had violated its right to fair administrative action.
The tax authority rejected the arguments. It told the tribunal that the main dispute had already been decided in its favour on 16th January 2026. No stay had been issued against that decision, which upheld the 2019 to 2021 transfer pricing assessment.
The earlier ruling confirmed an income tax assessment of about KES 4.96 billion ($38.1 million), including penalties and interest. This followed the tax authority’s examination of Del Monte’s related party transactions.
The tribunal relied on that decision in rejecting the argument that the withholding tax demand was premature.
The tax authority maintained that the Income Tax Act treats extra taxable income from transactions involving a shareholder or related person as a dividend. This means an actual payment to shareholders is not necessary for withholding tax to arise.
“The statutory language is clear and mandatory,” the tribunal said, agreeing with the tax authority.
It further held that the law did not make the deemed dividend dependent on the final resolution of a challenge to the main adjustment.