(NAIROBI, KENYA) – Kenya’s Employment and Labour Relations Court has upheld the dismissal of a senior Kenya Revenue Authority officer who cleared six containers before their ship arrived at the port of Mombasa, ruling that he was negligent in checking the cargo records.
However, the court faulted the tax agency for taking 14 months to dismiss the employee, identified in court as Mr KPS, after a disciplinary hearing, finding that the delay breached the constitutional requirement for timely administrative action.
Mr KPS moved to court in 2022 to challenge his April 2019 dismissal over the premature release of six containers carrying undeclared garments, which the tax agency said exposed it to revenue loss.
He sought reinstatement, damages for unlawful termination, compensation for time spent out of employment and payment of any outstanding dues.
The court dismissed the claim, finding that the tax agency had established a valid reason for his dismissal and followed a fair disciplinary process, despite the unexplained 14 month delay between his hearing and termination.
He was a Head Verification Officer at the Container Terminal, Kilindini Port. He joined the tax agency in January 2005, was suspended on 27th May 2016, and dismissed on 30th April 2019.
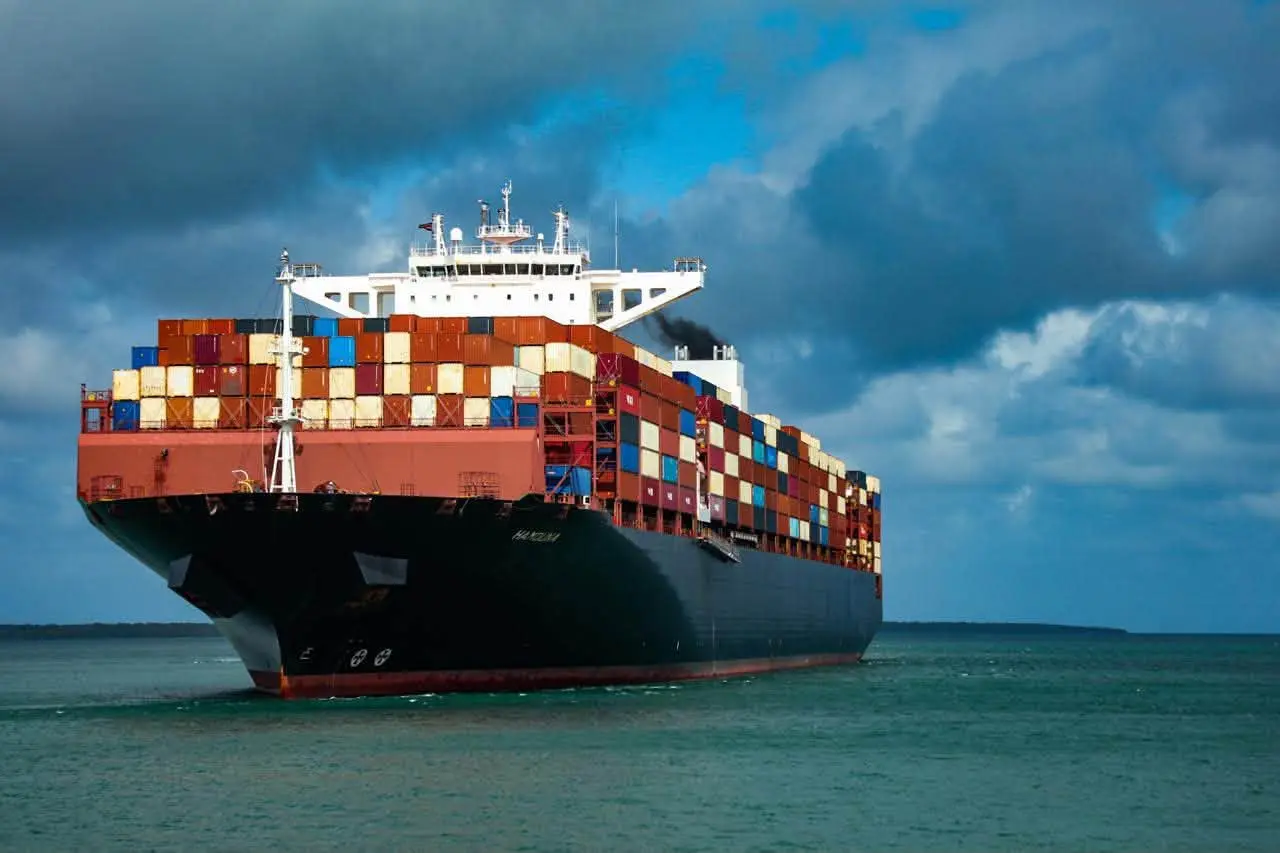
The tax agency said the releases covered six containers under two entries, made on 11th May 2016, before the vessel MV Katharina S docked on 13th May. The entries declared the cargo as ladies’ plastic shoes, but a check of the containers found them to contain new garments.
The first entry was released at 7.25 pm, 18 minutes after a verification account was posted. The second, covering five 40 foot containers, followed seven minutes later. Both records showed an expected arrival date of 14th May, although the vessel was still at sea.
The investigation reports put unpaid duty at KES 2.8 million ($21,500) for the first entry and KES 6.8 million ($52,200) for the second, a combined total of KES 9.6 million ($74,400).
The tax agency argued that the officer’s actions amounted to negligence and dishonesty, exposing public revenue and security to risk. The court accepted negligence but found no proof that he knew the goods were misdeclared, received money or dealt with the importer.
“The respondent has discharged its burden under Sections 43 and 47(5) on the negligence limb,” the judge said.
While the court found that the officer was negligent in releasing the containers, it ruled that the tax agency had failed to provide evidence linking him to deliberate wrongdoing or collusion with the importer.
“This court is not satisfied that dishonesty was proved. The reports say the officers acted knowingly and deliberately, but the respondent called no investigator and produced no evidence that the Claimant knew the goods were misdeclared, was paid anything or dealt with the importer,” said the judge.
The officer said he relied on records prepared by other officers and a Kenya Ports Authority system slip showing the containers in the port yard. He argued the vessel’s arrival date was an estimate and said he testified as a prosecution witness after an inquiry conducted by the Directorate of Criminal Investigations.
The court said he had not produced the ports authority slip or evidence that investigators had absolved him. It found the final internal check could not depend entirely on colleagues’ paperwork when the dates raised questions. No investigator supported the tax agency’s allegation of deliberate conduct.
The tax agency’s reports said its Investigations and Enforcement unit compounded the offence and recovered additional revenue, fines and penalties.
The court said recovery did not make the lapse minor. One container escaped interception, while an intelligence report led to the others being stopped. It found that he failed to question discrepancies in the records.
The court found the termination procedure fair since the officer received two notices to show cause, answered both and attended a committee hearing.
The tax agency did not produce the hearing minutes, a shortcoming the judge noted, but the court found no evidence that their absence made the disciplinary hearing unfair.
The disciplinary process lasted about 35 months. The tax agency’s code of conduct envisaged cases being determined within six months “as much as may be possible”, while the guidelines called for investigations within a month and action without delay.
The court ruled that, though the period between the hearing and termination was unexplained, the delay did not warrant compensation because the officer had not proved that it caused him any prejudice.
“The court finds that this unexplained delay was inconsistent with the expeditious administrative action required by Article 47 of the Constitution and with the respondent’s Code of Conduct,” the court said.
The officer received his basic salary, house and transport allowances and medical cover during suspension. The court said he did not prove lost opportunities or other harm caused by the delay, so it awarded no compensation.
Reinstatement failed because the statutory three year period expired on 30th April 2022. The employee added the request in January 2025, too late to revive the remedy. The tax agency said it had paid his salary up to termination, three months’ salary instead of notice and pension benefits.